 Zadi
Every card you own, one app that thinks about all of them.
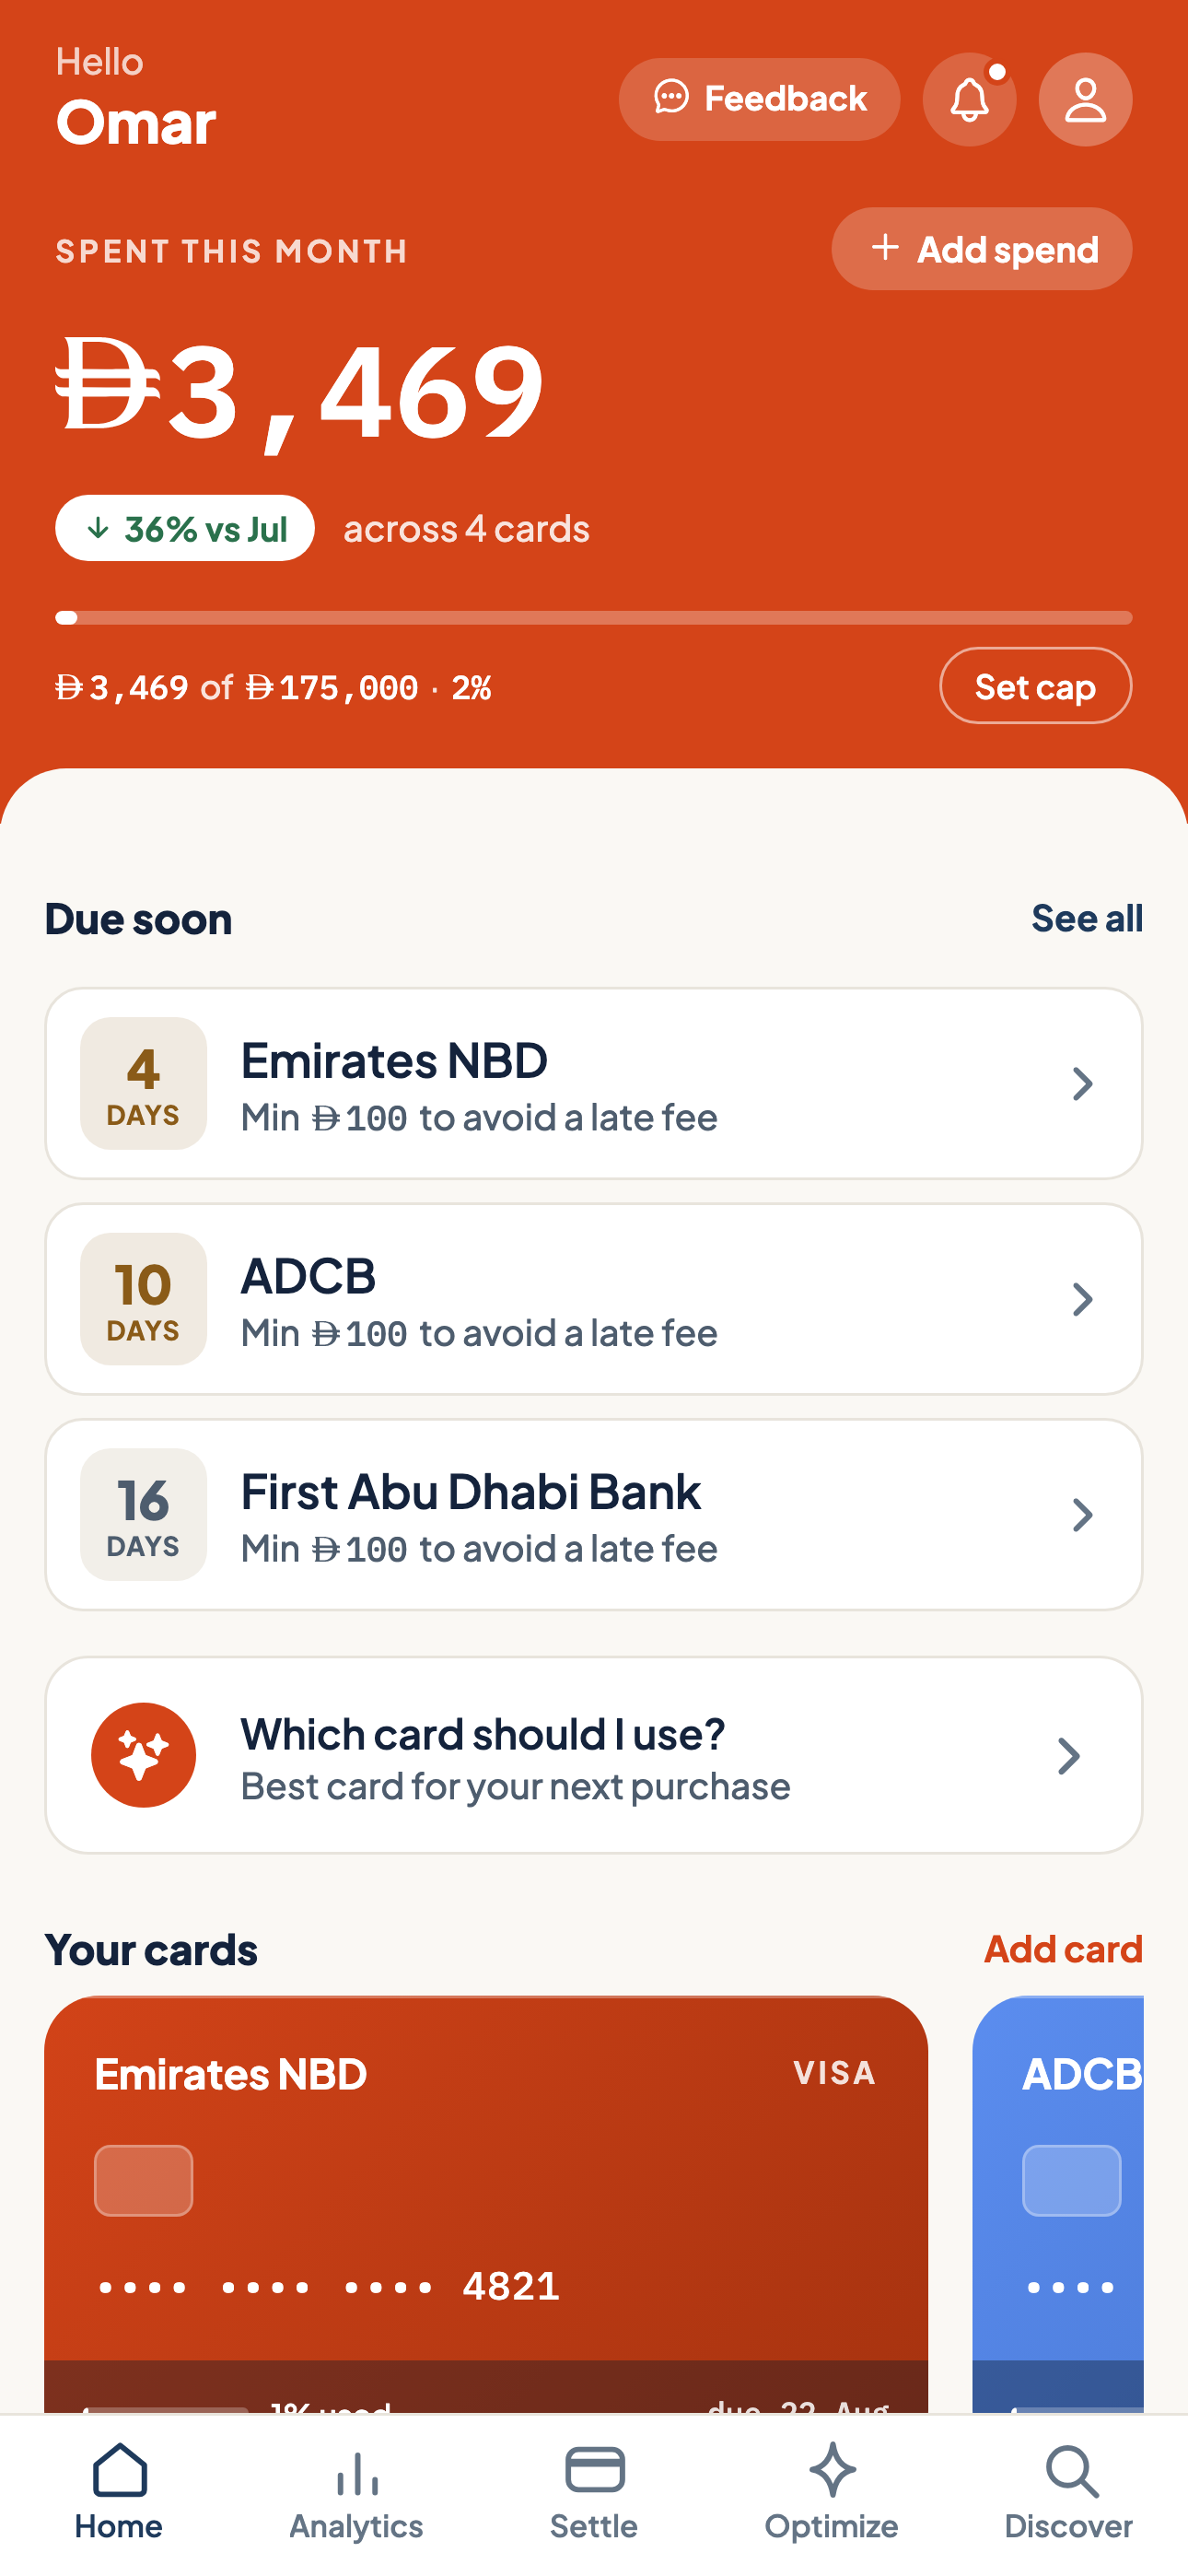
Zadi brings your credit cards from every bank into one place: what you owe, when it is due, which card to swipe, and what your rewards are really worth.
Sources: YouGov UAE survey; published UAE bank fee schedules and reward program terms.
The problem
No bank can show you a card it didn't issue.
A multi-card wallet in the UAE usually spans two or three banks. Each app shows its own slice, so the full picture lives in your head. That is where the money leaks.
Missed due dates
One forgotten date costs AED 230 to 300 in fees, and interest at 30 to 48% APR backdated to the day you spent.
The wrong card
Reward rates differ by card and by category. Paying with whichever card is on top quietly costs real dirhams every month.
Rewards nobody counts
No statement shows the gap between what you earned and what the right card would have earned. Points are real money, and they lapse in 12 to 24 months whether or not you noticed.
The product
One place that understands your whole wallet.
The whole picture, on one screen
Open Zadi and see what a bank app can never show you: everything, together.
- Combined spend and credit used across every bank
- Every due date in one list, with reminders that leave time to act
- Spending by category, month against month
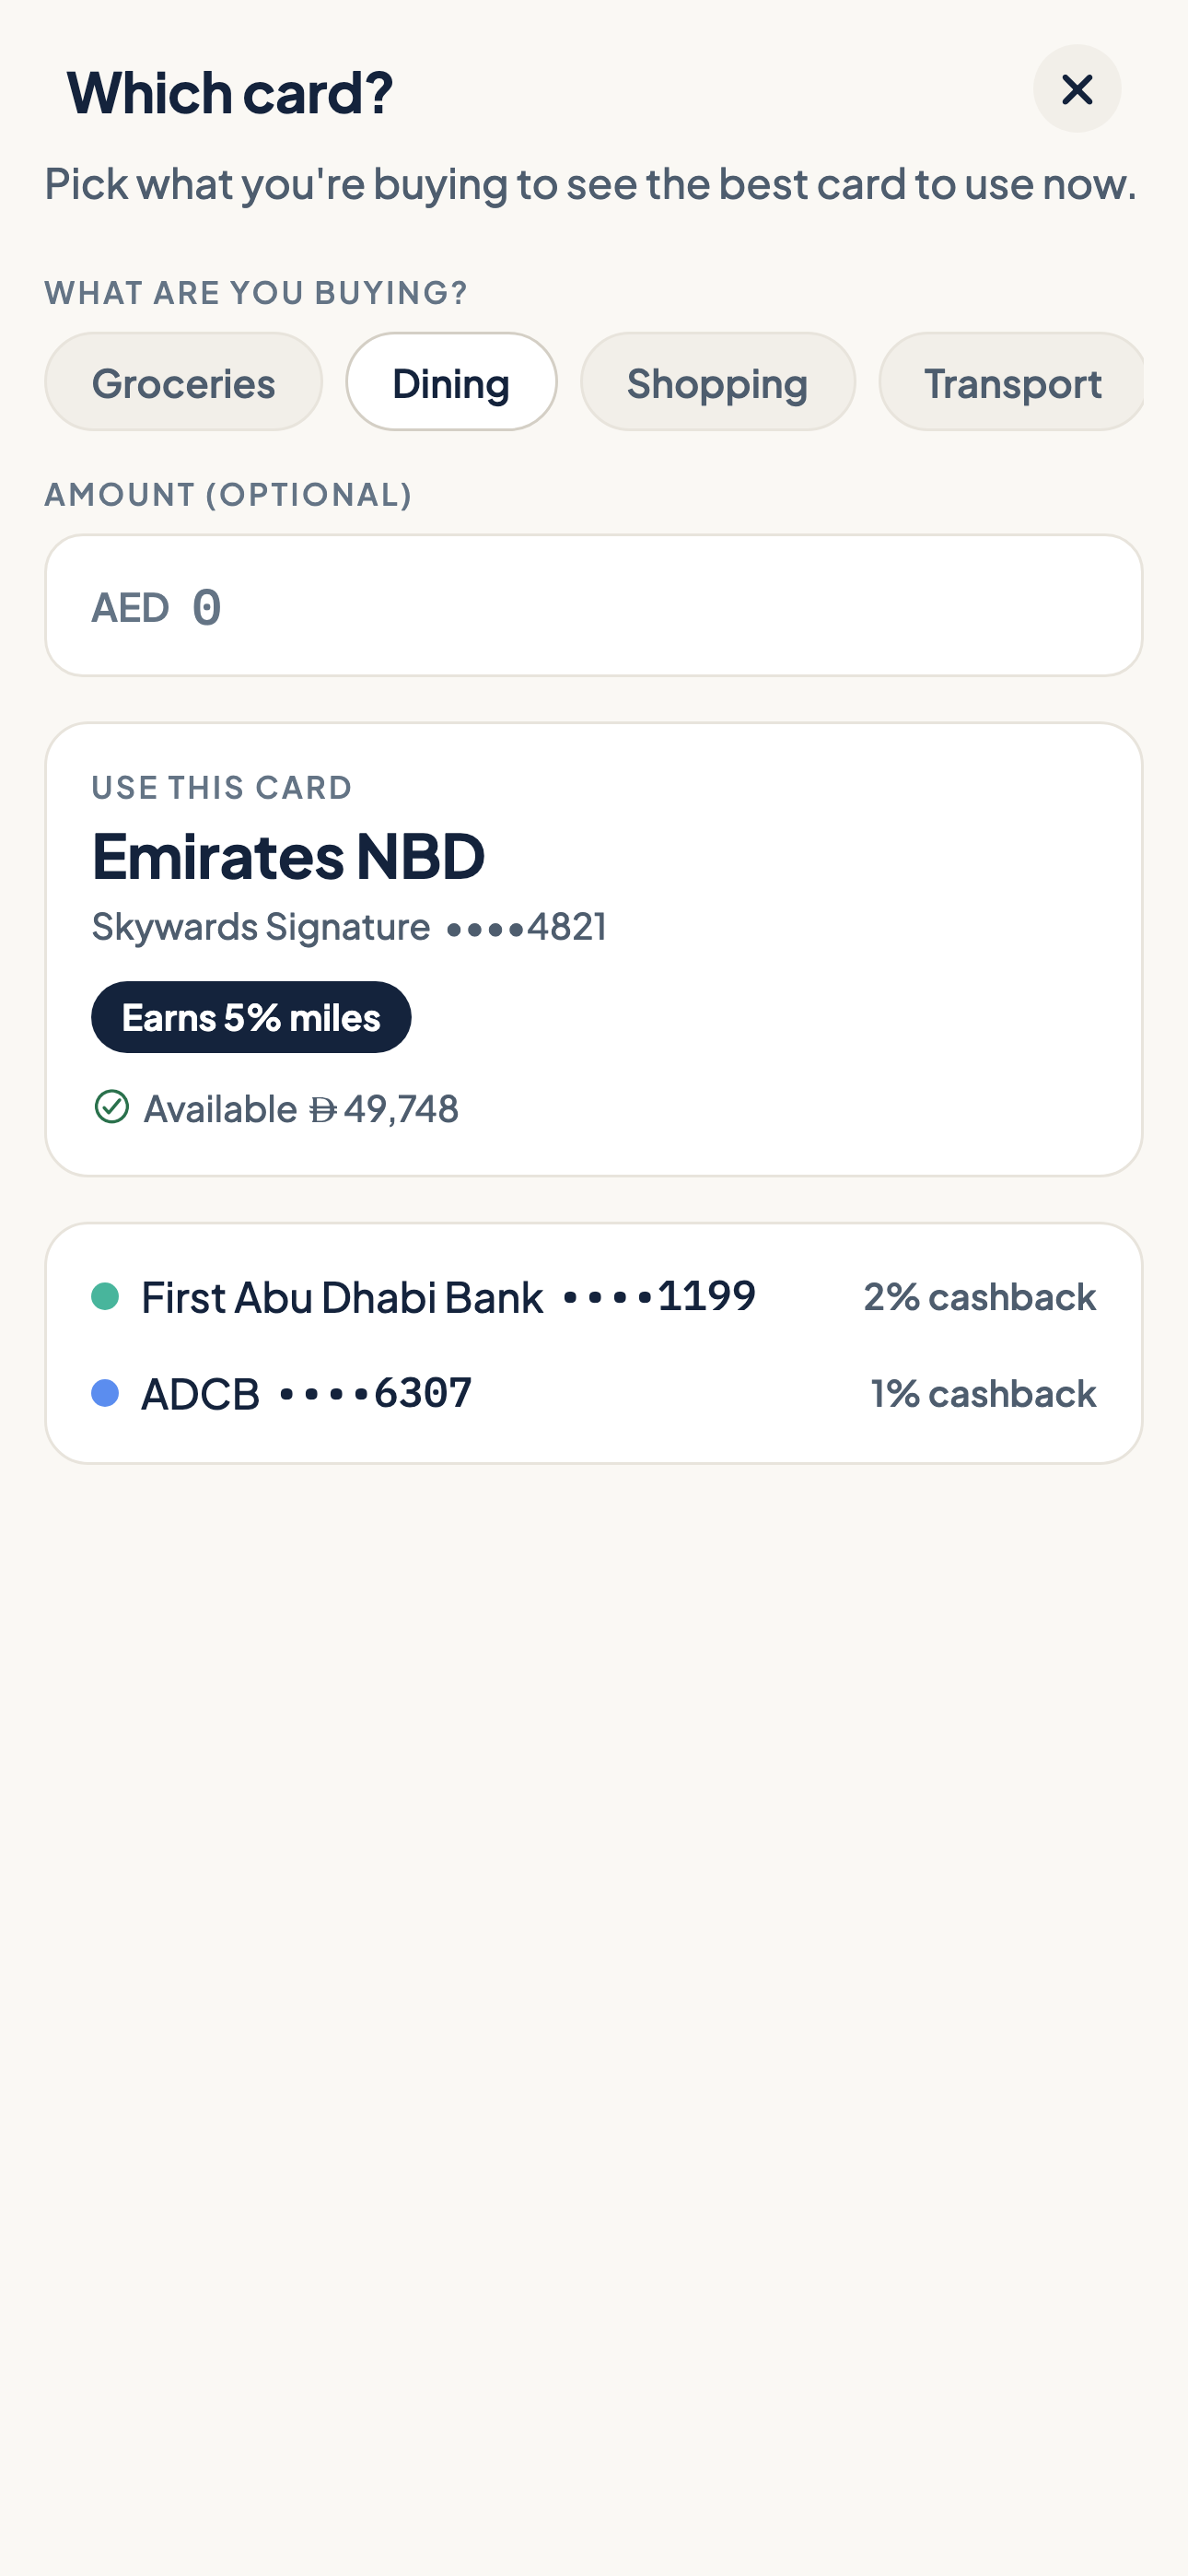
The right card, before you pay
At the till, tell Zadi what you are buying. It ranks your cards for that purchase and shows the answer in dirhams.
- Category bonuses, caps and card limits all accounted for
- Miles and cashback compared in dirham value, so 5x miles stops beating 4% cash on name alone
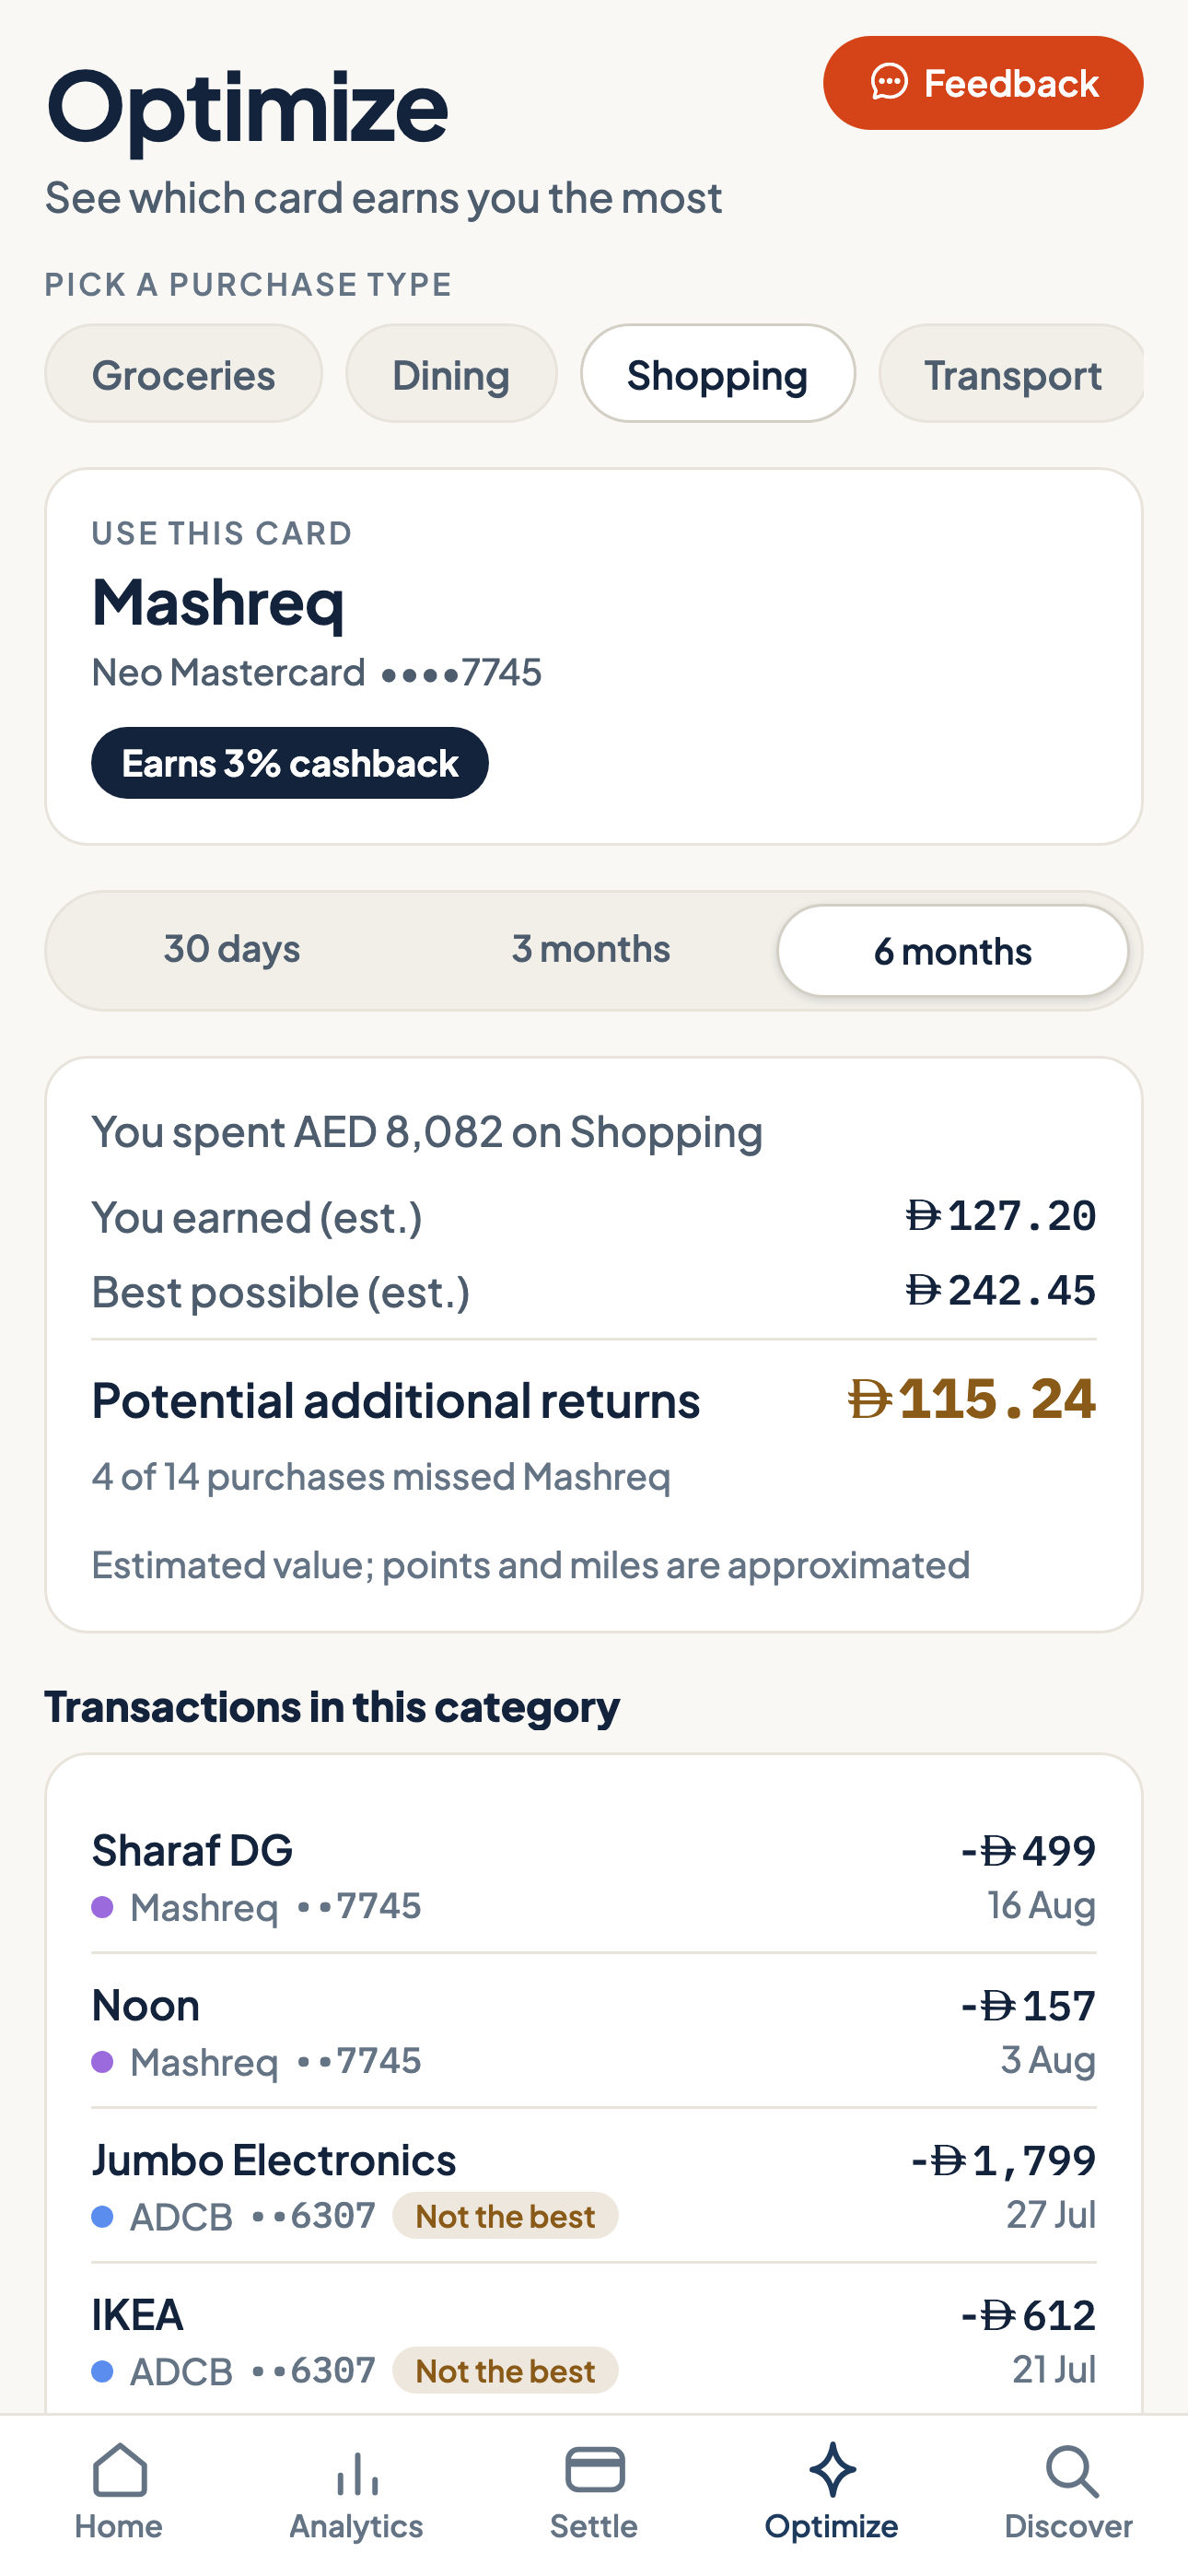
The money you didn't have to lose
Zadi counts what the wrong card cost you: the gap between the rewards you earned and the rewards your own wallet could have earned.
- Tracked per category over 30 days, 3 months and 6 months
- Counted in AED, so you know what changing the habit is worth
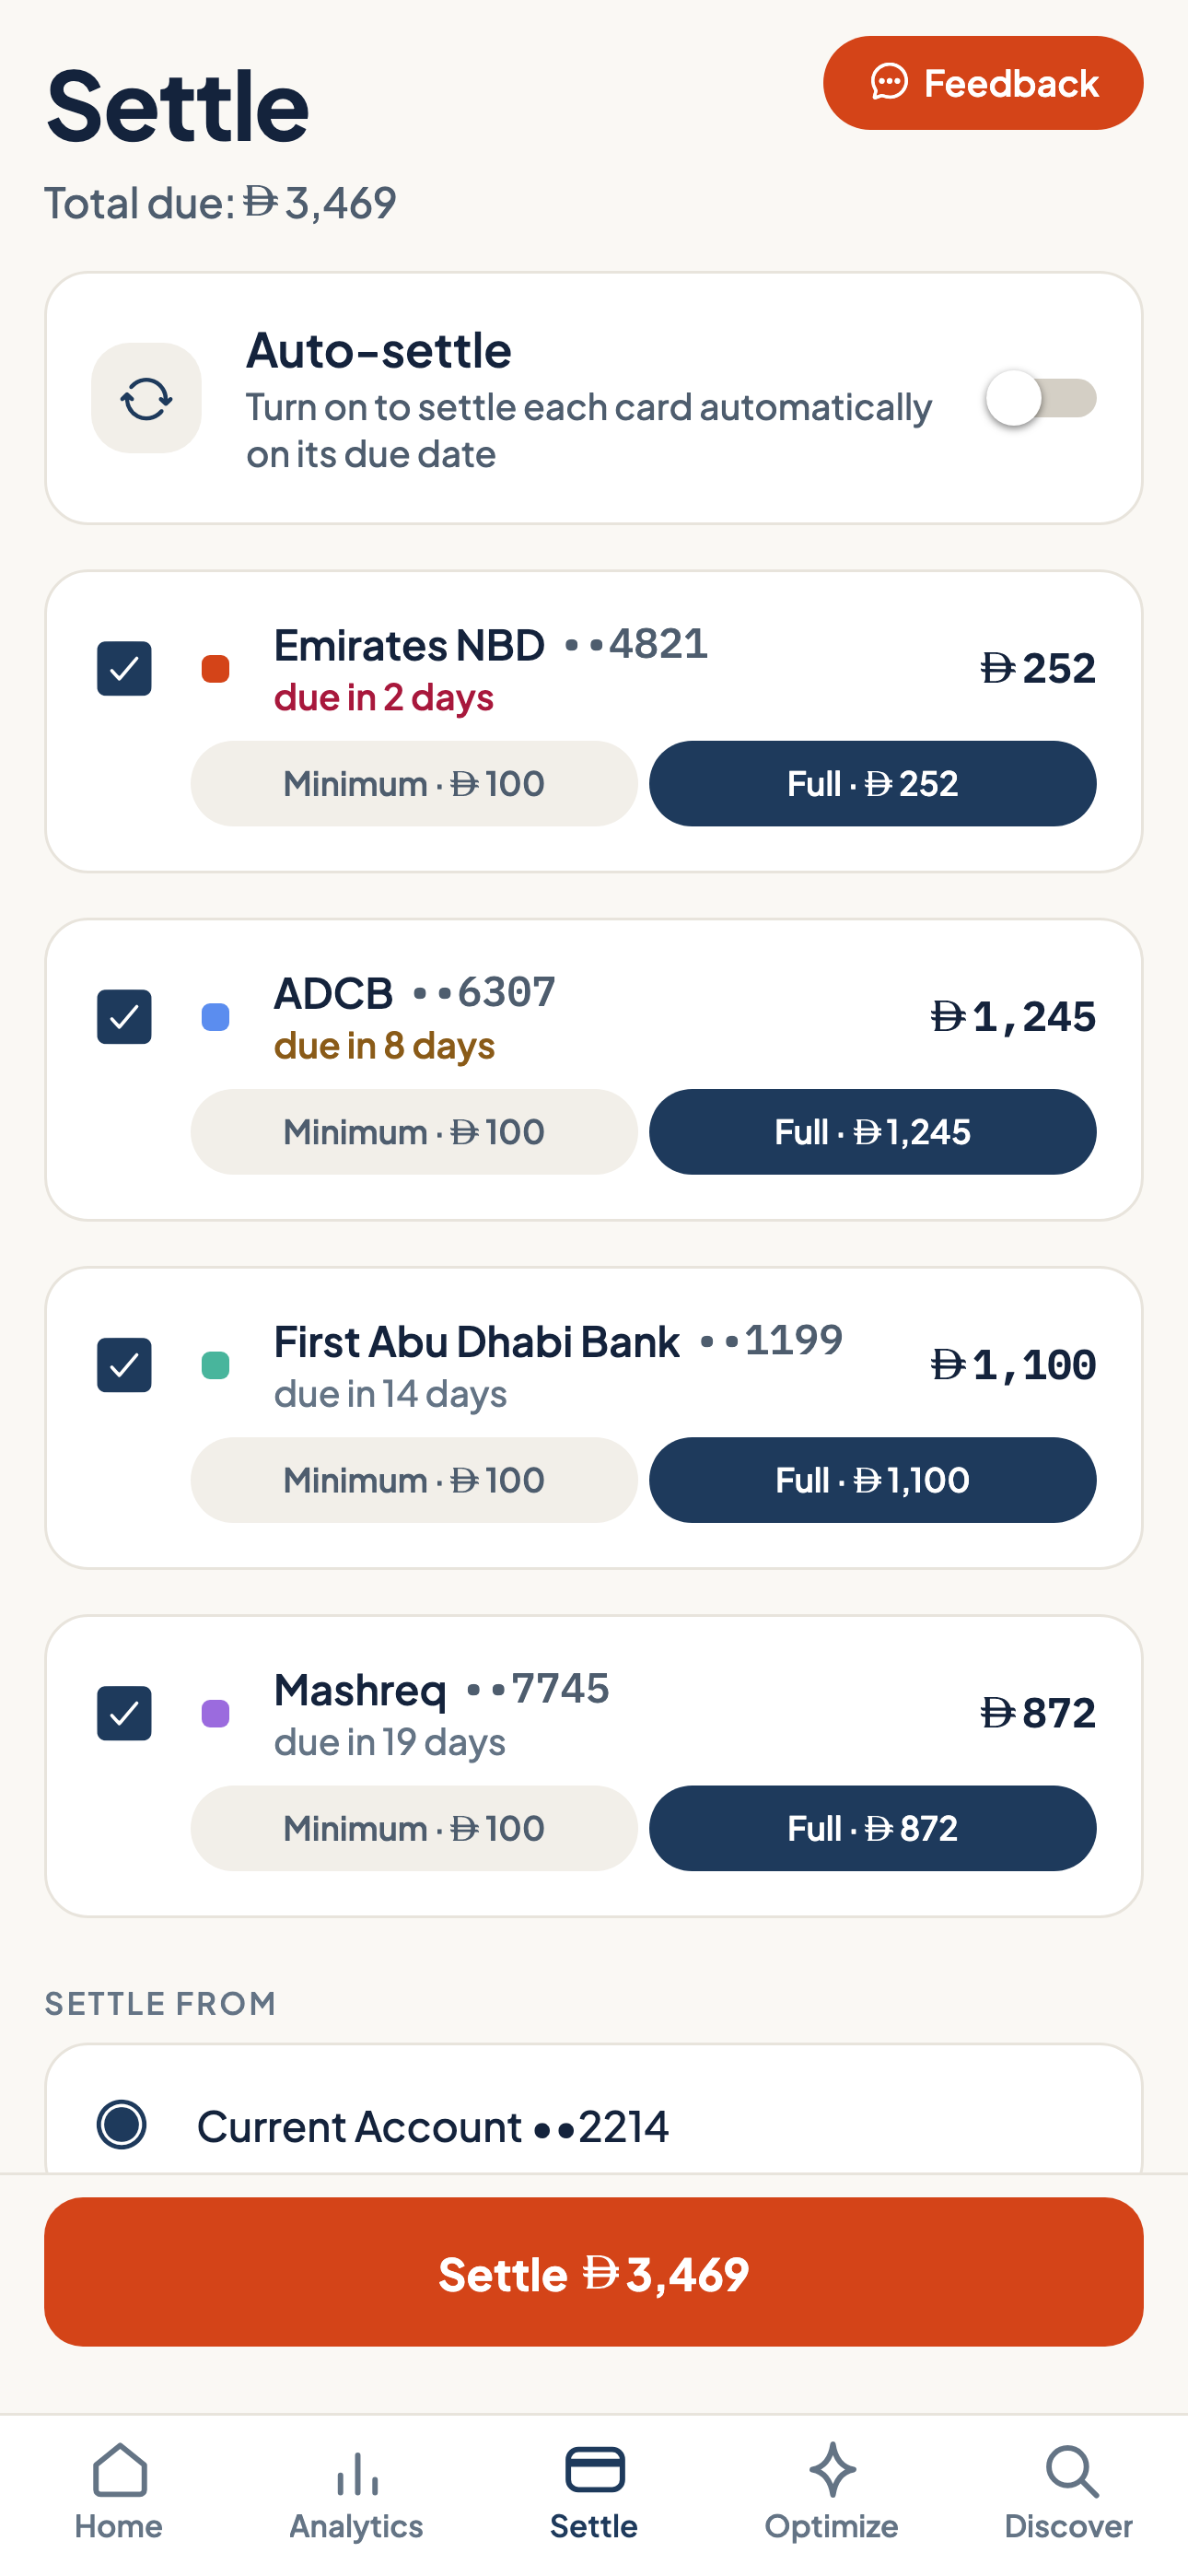
Every card's payment in one place
Settle gathers every card's amount due into one list and marks off what you have paid, so the month takes one look instead of three banking apps.
- The minimum and the full balance on every card, side by side
- Record a payment the moment you make it at your bank, and every balance stays right
- Paying from Zadi itself is on the roadmap and needs a licence first. Even then, money would move bank to bank, never through Zadi
The market, measured against you
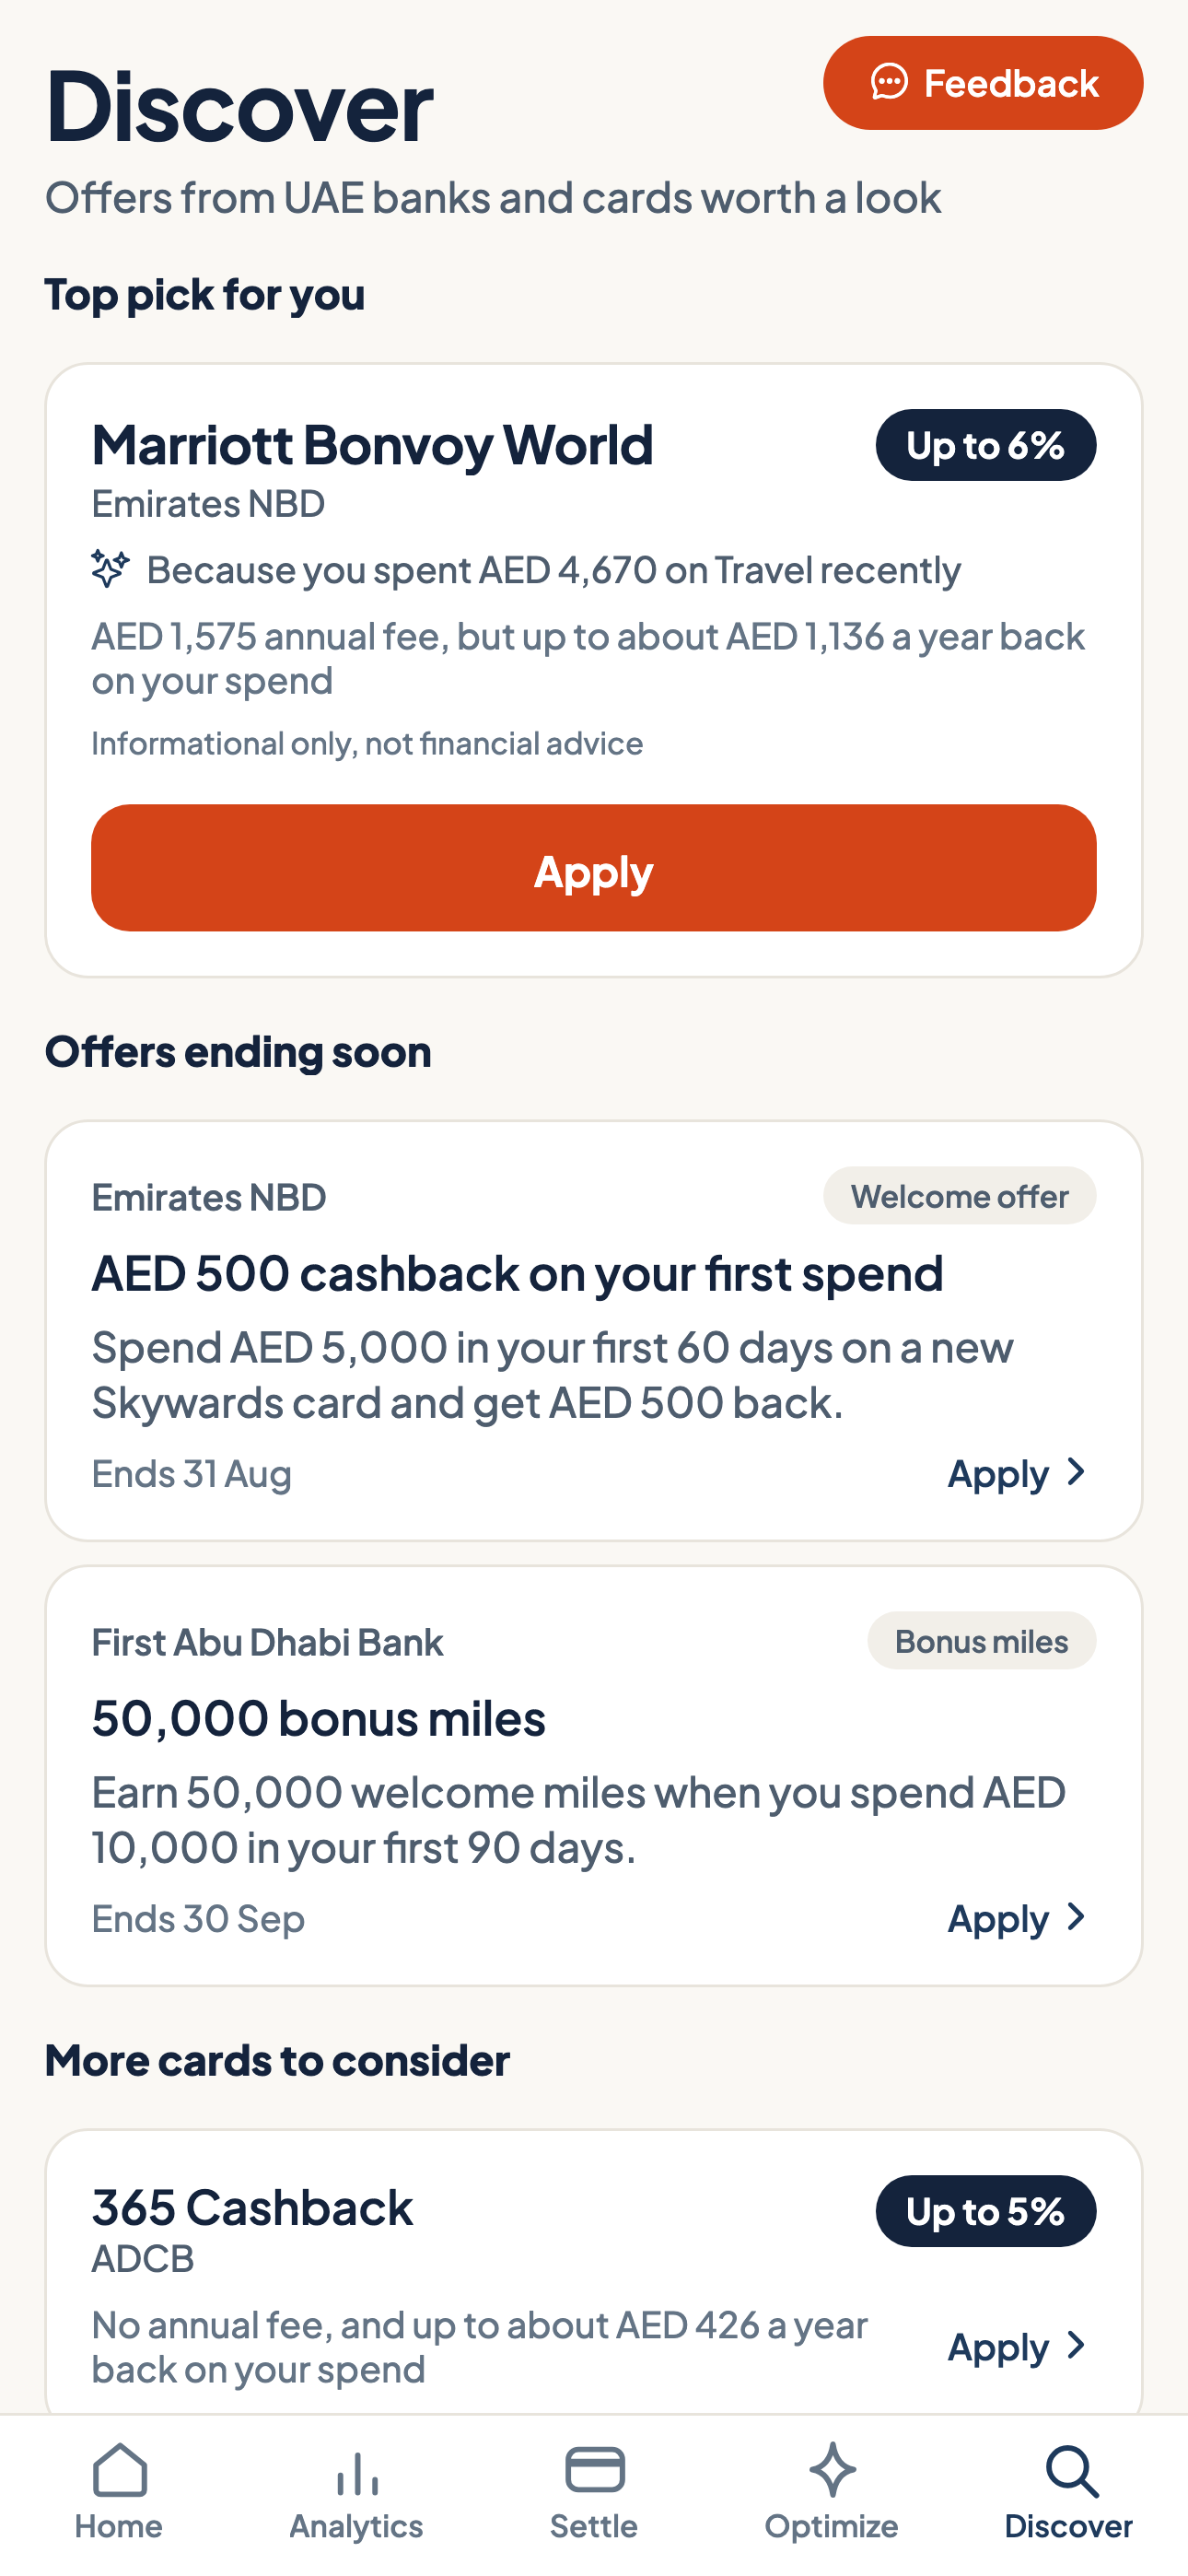
Discover ranks the cards on the market against how you actually spend, not against a generic profile.
- Each card's annual fee is part of the math, so a card only scores high if you'd come out ahead
- Informational, not advice: Zadi shows the numbers and you decide
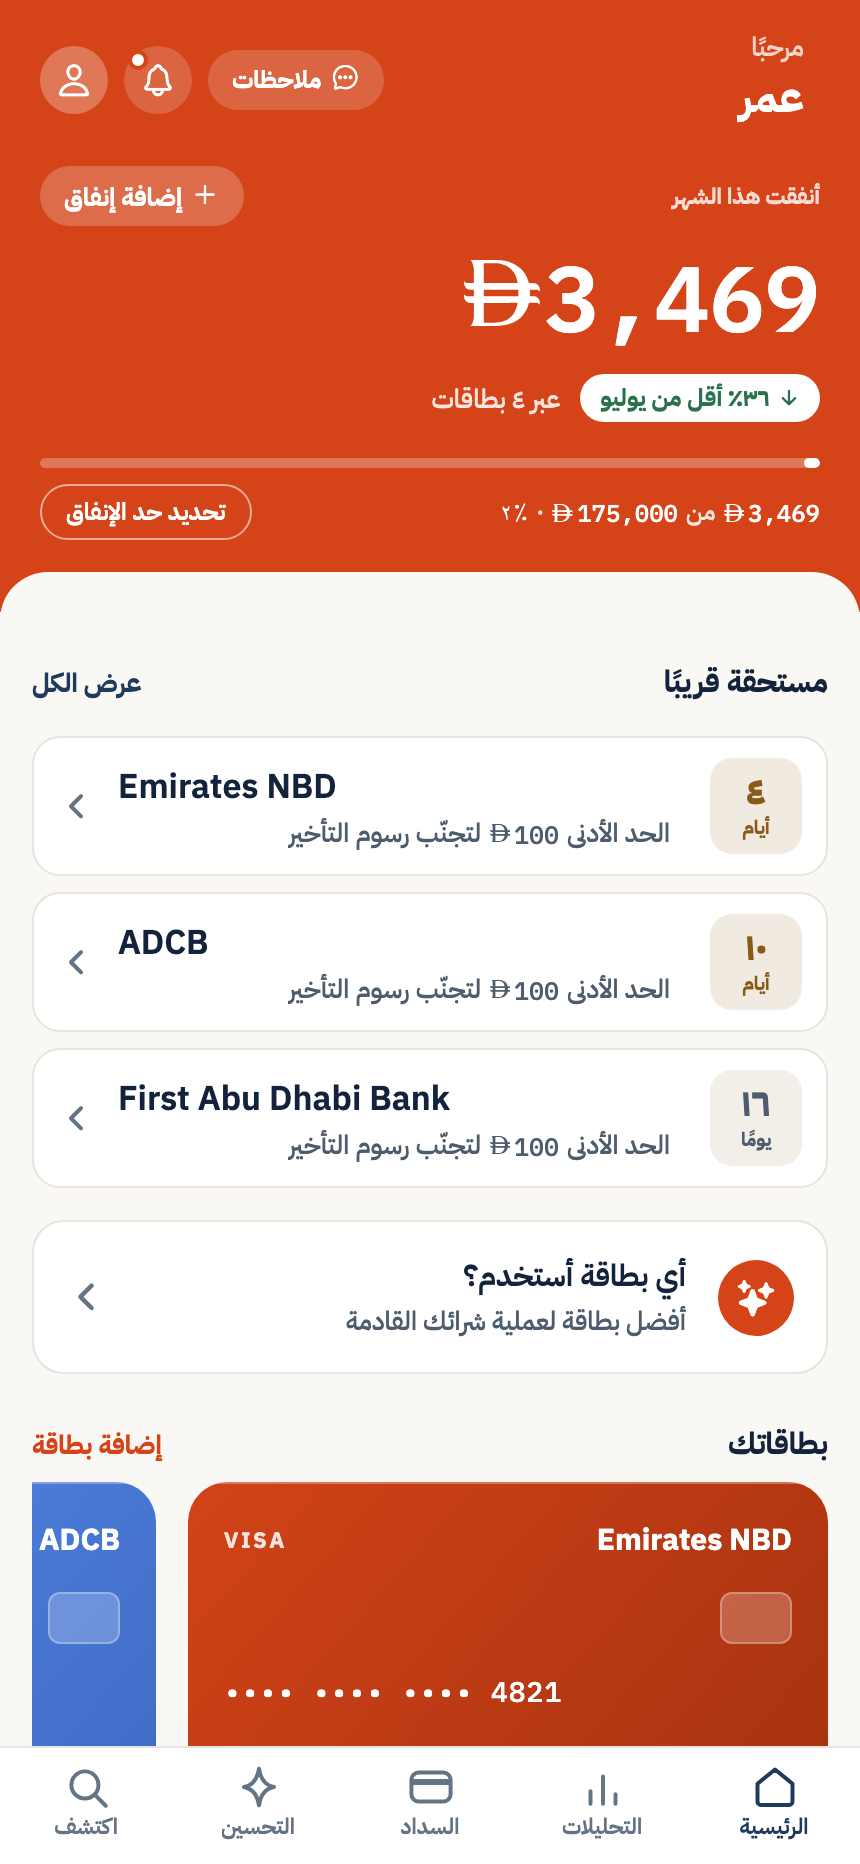
Zadi, in Arabic
Switch language once and everything follows: every screen, every date, every dirham amount.
How it works
Set up in minutes.
Add your cards
Add a card in under a minute: the bank, the last four digits, the limit, the statement and due dates. Direct bank connections through Al Tareq, the Central Bank's open finance rails, come once Zadi is licensed for them, and your login would stay with your bank either way.
Zadi maps your wallet
Every card's balance, limit, due date and reward program lands in one place and stays current. Spending sorts itself into categories.
Zadi keeps watch
Reminders arrive before every due date. The best-card answer is a tap away. Mark a card settled the moment you pay it, and the numbers follow.
The demo
Every screen, explained in under two minutes.
Security and trust
How Zadi handles your money and your data.
Your money never touches Zadi
Zadi holds no funds and moves none. Settle records a payment you have already made at your own bank, so nothing leaves an account through us. Payment initiation, once Zadi is licensed for it, would move money from your bank to your card issuer and never through Zadi.
Consent you control
Nothing is connected unless you ask for it, and today nothing is: you enter your own cards. When connections arrive through Al Tareq, the Central Bank's own rails, you would approve them at your bank and could revoke them there any time. Your login would stay with your bank, and Zadi would receive only the card data you consented to share.
Your data stays yours
Every record is isolated to your account with row-level security, encrypted in transit and at rest. Your data is not for sale, and deleting your account deletes it.
Built for the regulated rails
The Central Bank's open finance framework names credit cards in its scope, with consent rules for data sharing and for payment initiation. That framework, and the authorisation it requires, is the route Zadi is working through.
The founders
We kept paying late fees with money in the bank.
Between us we carry more cards than we like to admit. Zadi is the tool we needed and could not download.

Hussein Tawfik
13+ years of experience in leading organizations across consulting, technology and consumer goods, including Talabat, BCG, Meta and P&G.
LinkedIn
Mostafa Asseel
13+ years of experience in leading organizations across e-commerce, retail and technology, including Amazon, Carrefour (MAF), Microsoft and Oracle.
LinkedInFAQ
Questions people ask us.
Does Zadi connect to my bank account?
Not today. You add each card yourself in about a minute, and Zadi holds no connection to any bank. Direct connections through Al Tareq, the Central Bank's open finance rails, are the plan, and they need Zadi's own authorisation first. When they arrive you would approve access at your own bank and could revoke it there at any time, and Zadi would never see your banking login.
Is my money at risk?
No. Zadi never holds or moves money, and it has no access to any account you can pay from. Settle records a payment you already made at your own bank. Payment initiation, once Zadi is licensed for it, would send an instruction you approve at your bank, and the money would move from your bank to the card issuer and never through Zadi.
What does it cost?
The core view of your cards and due dates is free. Zadi Pro, with the full optimizer and deeper analytics, is AED 39 per month. During the beta, everything is free.
Which phones does it work on?
iPhone and Android, in English and Arabic with a fully mirrored right-to-left layout.
Is Zadi giving me financial advice?
No. Zadi shows you information about your own cards: dates, rates and reward maths. It does not provide regulated financial advice, and card suggestions are informational comparisons of products you already hold.
How do I get in?
Request an invite and tell us which phone you use. We onboard testers in small batches so every one of them gets our attention.
Make every dirham go further.
We are onboarding UAE testers in small batches. Tell us which phone you use, and the next invite goes to you.
Request an invitehello@zadi.ae · United Arab Emirates